June 2026 Dividend Income Update
Hi DIY Investors!
Welcome to a new month and our new tally: our June 2026 Dividend Income Update.
For established readers (and any new readers that recently joined my free newsletter (thanks folks!)), this is our monthly update to share how we are now spending our retirement income.
This is the portfolio structure we established back in 2009 and have maintained largely to this day now in early retirement:
- We invest in a mix of about 20+ Canadian stocks for income and growth, and
- We invest in low-cost equity ETFs for extra diversification.
That’s our equities.
Everything else is now in cash / cash equivalents for the rest of 2026 spending.
June 2026 Dividend Income Update
Last month I focused on bonds (or lack thereof) in our portfolio.
This month, I’ll just focus on our dividend and distribution income for our retirement income spending, from our ETFs.
Certainly, our income updates would be MUCH HIGHER if I didn’t invest in any ETFs for growth.
However, I like growth in our portfolio. A lot of growth.
Our ETFs are there for that ex-Canada extra diversification and for that primary reason.
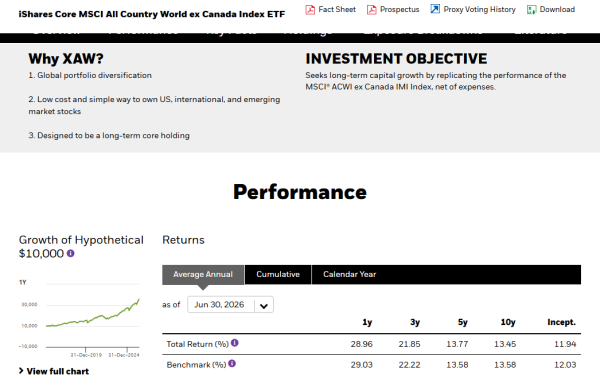
For example, we’ve owned XAW since just after the fund’s inception in 2015 (we’ve owned it since early 2016). Those 10-year returns are now in:

Image sources: iShares.
Very impressive for boring investing ~ 13% annualized – that’s from doing nothing but staying invested and simply adding more ETF units with time for ex-Canada returns…
What does this have to do with our June 2026 Dividend Income Update?
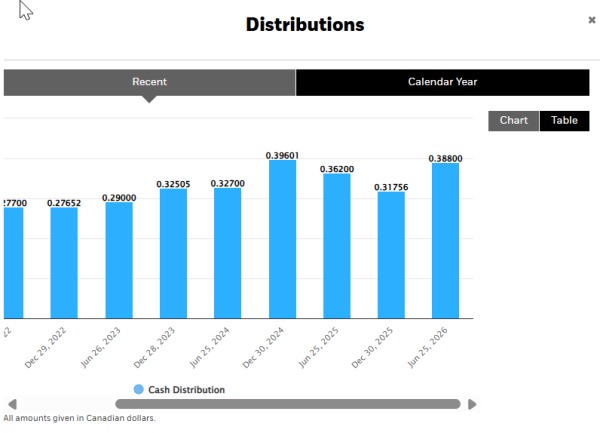
Well, even if yields are lower in our portfolio, by owning the ETFs we do, those low-cost funds still deliver some income to us. That income is part of these updates. XAW distributions in particular happen twice per year and the recent distribution increase over winter 2025 was very kind to us:
With low-cost ETFs mixed in with our Canadian stocks as part of our hybrid portfolio:
- Our portfolio is up in value.
- Our dividend and distribution income is up for spending.
Win-win.
We haven’t yet sold any ETFs to fund our early retirement lifestyle but I suspect we will in the coming years, at least some selling in registered accounts (RRSPs/RRIFs, LIFs) to fund more international travel.
Thanks to the jump in XAW distributions last month along with recent big bank dividend increases and any reinvested dividends from them last month, our latest projected annual dividend income (PADI) update tells me we’re on track to earn about $85,877 this calendar year.

As mentioned earlier this year, we are not likely to reach our year end target of earning $90k this year without more investing but we shall see…
Even without any investing since January TFSA contributions were made in low-cost funds, dividend and distribution raises alone have added almost another $2,000 in spending YTD.

For reference in any monthly update, I’ve posted some important FAQs related to our portfolio income journey and reporting here. For example, I don’t include my future workplace pension nor any government benefits in these updates. We’re still far too young to accept those income streams!!
I continue to share these projections never to brag – I don’t share this information to boast about anything.
Rather, I share these updates to keep me/us accountable and to highlight what a long-term, disciplined (hybrid) investing approach via a mix of stocks and ETFs can (and does) deliver – should you wish to enter early retirement too.
These results can be the same or even more (!) if you follow a similar investing path.
I look forward to sharing the next update with you including more answers to reader questions in the next update.
Do share: how much income does your portfolio generate for you? If you don’t measure that, why not?
Mark
Mark

My name is Mark Seed – the founder, editor and owner of My Own Advisor. As my own DIY financial advisor, I’ve reached financial independence and I’ve retired from the workforce in my early 50s. Now, I share my lessons learned for free on this site. Join the newsletter read by thousands every week.