Has the crypto industry become just another Washington, D.C. lobby group?

Powerful corporate interests have long held outsize sway in Washington, D.C., using their deep pockets to influence elections and to hire former regulators to push preferred policies to law makers. These practices have made some industries a permanent part of the country’s political fabric, and given rise to unflattering monikers like Big Oil or Big Pharma or Big Food. In recent years, a newer industry has joined their ranks—one that in quainter days went by the “blockchain community” but today can more accurately be described as Big Crypto.
First arriving as a major player on the political scene in 2024, Big Crypto—led by firms like Coinbase and Ripple—has immersed itself in all the grubby ways of Washington. That was apparent last week when the industry’s biggest Super PAC revealed it would spend $30 million to influence the outcome of the U.S. Senate race in Ohio. Meanwhile, its biggest trade group, the Blockchain Association, is looking for a new head after the current one—a revolving door hire from the CFTC—decided to step down after barely a year on the job, despite pulling in a salary of at least half a million dollars.
One can only wonder what Satoshi Nakamoto would make of all this. When he published “Bitcoin: A Peer-to-Peer Electronic Cash System” in 2008, it was as part of a small group of libertarians who distrusted banks, and who distrusted government even more. This ethos persisted among crypto true believers for years and, for a long time, even many blockchain executives wanted little to do with Washington, D.C.
The decision by crypto’s current generation of leaders to trade in these ideals for swamp-style politics can, therefore, be seen as a deep betrayal. On the other hand, you can argue they had no choice. By 2024, it had become clear that then-Chair of the SEC, Gary Gensler, was waging an obsessive and bad faith campaign to destroy the crypto industry altogether. In this environment, firms like Coinbase and Ripple faced a fight-or-die situation and did what it took to survive—which, in this case, was playing the Washington game.
The question is where all this goes next. If you accept that politics have become an intrinsic part of crypto, the issue isn’t so much that blockchain companies are flexing their muscles in Washington, but that they are doing a bad job of it. The anecdotes from last week are a prime example. Sure, Ohio’s Democratic Senate nominee has a dim view of crypto, but it feels unwise to wage a $30 million scorched-earth campaign against him at a time when he and his party are poised to take back one or both houses of Congress. Likewise, the failure to hire an effective leader for the Blockchain Association has diminished the industry’s influence in the Capitol.
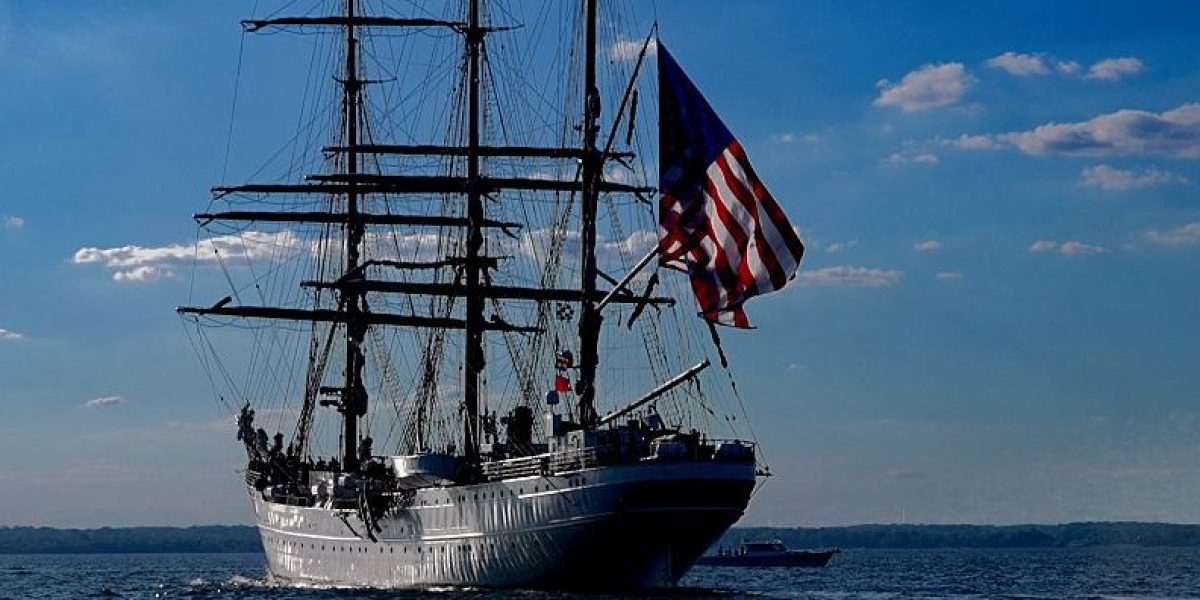
The crypto industry has found plenty of people in Washington willing to spend its money. Now, let’s see if it can achieve the harder strategic goal of developing a political strategy for the current era—one where it is no longer an underdog industry fighting a hostile government, but a dominant fixture in Washington’s corridors of power. To use an historical metaphor popular in the venture capital world, this is a situation where “the pirate becomes the Navy.”
For crypto companies, this means accepting more of the responsibility that goes with taking over an ever-greater portion of the world’s financial system. It also means doing more to work on the industry’s image at a time when, according to several polls, crypto is even less popular in the eyes of the public than Big Oil or Big Pharma. Right now, too many crypto executives want to be seen as upstart rebels even as they wield significant power in Washington, D.C. You can’t do both.
Jeff John Roberts
[email protected]
@jeffjohnroberts
DECENTRALIZED NEWS
Bitcoin hit $87,000 and the broader crypto markets are ripping, but the biggest to-the-moon story this year remains ZCash, which reached a new record high (Fortune)
In a back-to-the-future moment, a new tie-up between Payward and Ledger will let users store tokenized stocks offline on the hardware maker’s cold storage devices (Fortune)
Microsoft and Coinbase took down the EvilTokens network, which sold AI-powered DIY phishing kits on Telegram that were used to defraud a wide range of businesses (Fortune)
MoonPay accelerated its push into tokenized securities with the $60 million acquisition of back-end brokerage service North Capital Investment Technology (Fortune)
In a deal that would have been inconceivable five years ago, Binance invested $100 million in one-time stablecoin rival Circle and plans to distribute USDC in developing markets (Fortune)
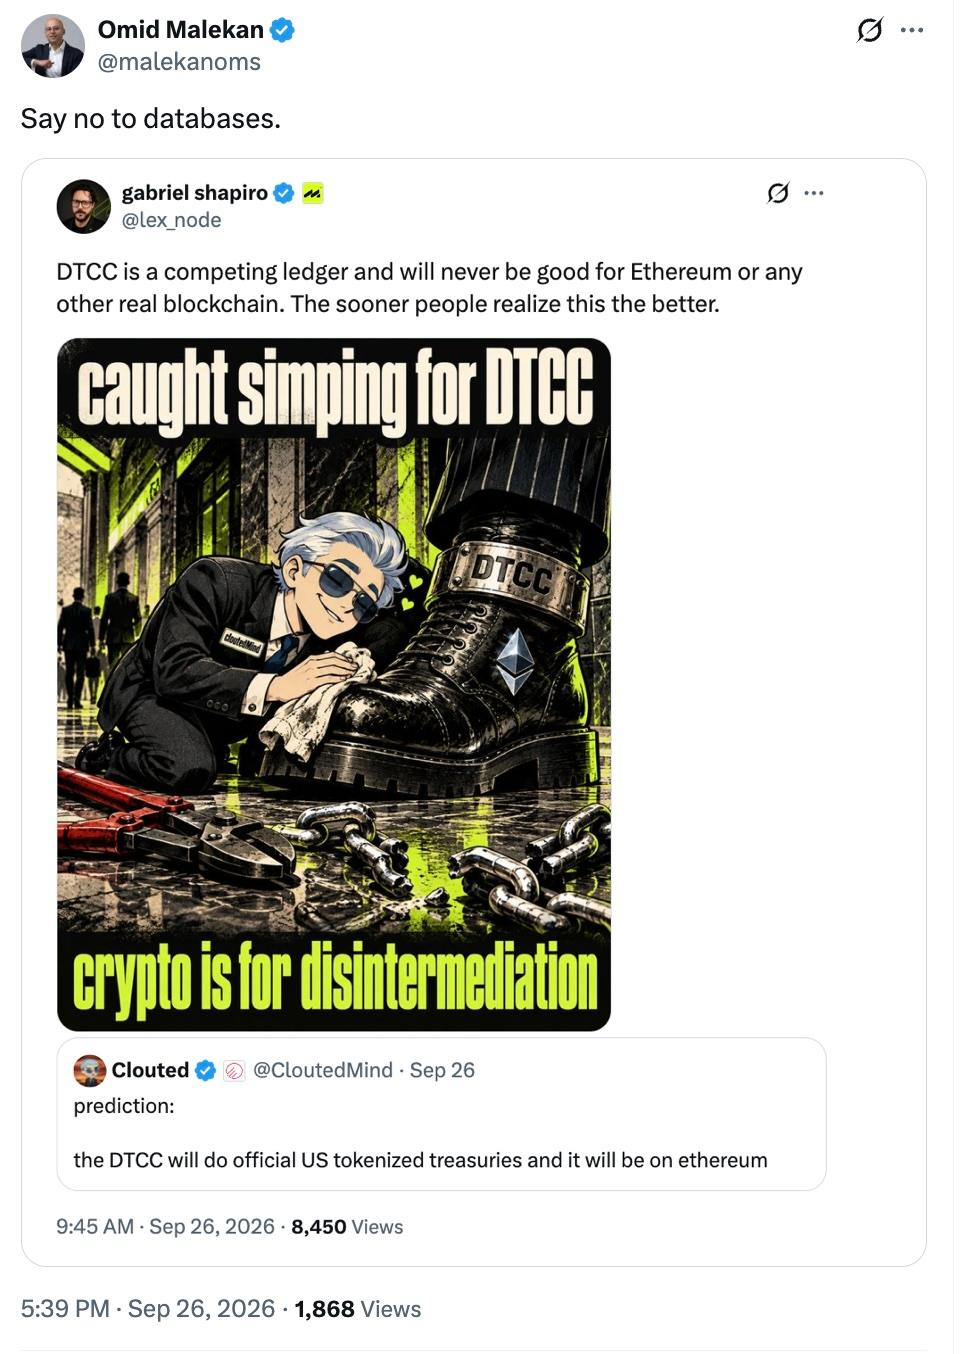
MEME O’ THE MOMENT