
September 2026 Dividend Income Update
Hi Readers,
Welcome to our latest update: September 2026 Dividend Income Update!
For established readers (and any new readers that recently joined my free newsletter here (thanks folks!)), this is our monthly update to share how we are earning and now spending our annual dividend and distribution income in early retirement…
Since late-2025, our portfolio structure was and remains:
- Ownership in just over 20 Canadian stocks for income and growth, and
- We invest almost 50% of our portolio in some low-cost equity ETFs for extra diversification.
That’s 90% of our total portfolio.
Everything else (10%) remains in cash / cash equivalents for near-term spending…including more travel I will share later on!
September 2026 Dividend Income Update
Five months into retirement and I’m settling in.
It’s been a transition for sure.
There are a few lessons learned to date and I’m sure there will be more in good time!!
It’s certainly an odd feeling spending from the portfolio vs. saving – a habit I’ve needed to reverse after 30+ years of being a saver.
But this is OK and necessary.
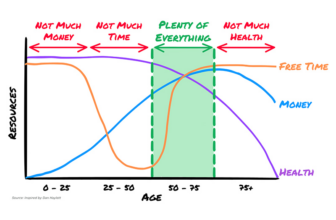
I’m hardly 65, let alone even in my mid-50s yet, but I read something like two million more Canadians will be 65 or older within the next decade (!)
There is real fear with spending from your portfolio for some:
- People are living longer – a 65-year-old today could spend 25 to 30 years in retirement. That’s a gift but also pressure on retirement savings.
- People are retiring without defined benefit (DB) pension plans, forcing more stress on personal retirement savings.
- Healthcare and inflationary costs will continue to rise – inflation is a wealth-killer and puts more pressure on retirement savings when the cost of living continues to go up.
- Sequence of returns risks are real, they happen, and even after the “retirement risk zone” investment returns can fluctuate wildly year to year. So, a market downturn let alone a prolonged market downturn can have major impacts on retirement savings.
Retirement isn’t one-size-fits-all
So how do I cope and move forward?
Retirement is one of life’s biggest transitions – and I’m still working through it.
As part of this month’s update, here are the key financial things we’ve been successful on and I will continue to update you on:
1. I/we continue to focus on cashflow from the portfolio vs. net worth vs. total reliance on capital gains.
What I mean by is cashflow = sum of dividends, distributons, interest and capital gains.
It was always the plan to ensure we had enough cashflow from our portfolio in retirement to cover expenses. Using 5% annualized returns, that will be the case until age 95 and our portfolio should never run out of money. If we get higher than 5% returns in the coming 30-40 years, we’ll just spend more money.
2. I/we have our cash wedge and are spending money from it – first.
In early retirement I/we continue to believe there are key risks to navigate: inflation risk and markets/sequence of returns risk. The Cash Wedge helps combat these near-term. I actually started thinking about the Cash Wedge years ago and we’ve now implemented it.
3. I/we have a budget (and try to stick to it)!
We have a retirement spending formula for the 1. basics (needs), 2. fun (wants) and 3. we keep about 10% buffer on top just in case. We’ve built our portfolio in a way that delivers dividend and distribution income that covers the needs every year. Cashflow, including capital gains, covers the fun and buffer and then some.
September 2026 Dividend Income Update
Financial planning can feel overwhelming if you’re just starting to learn about these concepts for retirement, but if you’ve been practicing the process of income planning for many years leading up to retirement, well, I suspect the skills you have are plenty good enough whenever you decide to retire.
You will simply need to fine-tune those income planning skills and adopt a new mindset that spending is OK and it’s what you’ve been planning for all along.
There’s no one-size-fits-all approach to drawing down one’s retirement savings although there are some best practices to consider.
Some prefer a dividends only approach.
Some prefer a capital gains approach.
Others prefer a blend – we’re in this category.
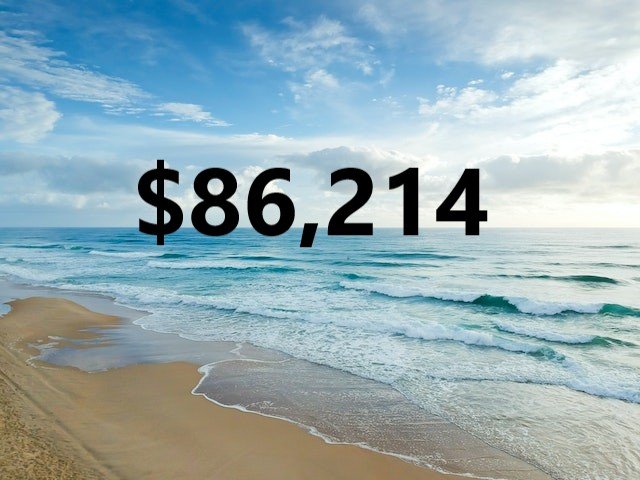
In our approach, we’re on track to earn the following this calendar year in projected dividend and distribution income:

For reference in any monthly update like this, I’ve posted some important FAQs related to our portfolio income journey and reporting here. For example, I don’t include my future workplace pension that I will turn on in a few years, nor do we include any government benefits in these updates. We’re still far too young to accept all of those income streams!!
I continue to share these projections never to brag but to inform what is possible for your retirement income planning and to be very frank, to keep yours truly accountable too!
I can help you with your own retirement income projections and taxation considerations as part of that work, in a low-cost way, here anytime.
Whatever your investment strategy is, I look forward to hearing and reading your income planning updates in the comments.
Keep me posted in the comments section about how your portfolio is doing including anything on our new YouTube channel.
Happy Investing!
Mark